Income Certification Requirement
Under the current tax framework, Unit Trusts operate as pass-through vehicles. Income tax applies at the unit holder level rather than at the fund level.
However, the proposed Amendment Bill introduces a new requirement.
- Unit Trusts must issue detailed income certifications to investors.
- These certificates must disclose income earned, exempt amounts, withholding taxes deducted, and any additional information specified by the Commissioner General of Inland Revenue.
- Funds must issue the certificate within five months from the end of the relevant year of assessment.
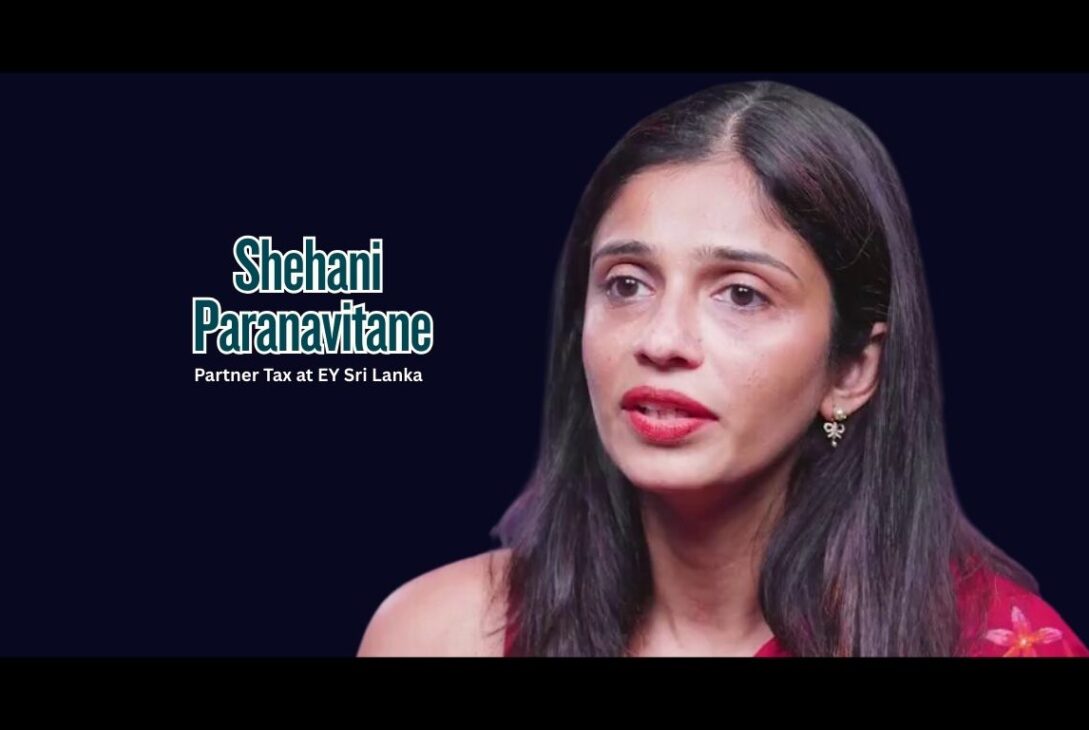
According to Shehani Paranavitane, Partner Tax at EY Sri Lanka, “the Bill proposes a significant consequence for non-compliance. If a Unit Trust fails to provide certification, authorities will treat it as a company for income tax purposes.”
This measure is intended to encourage consistent disclosure and strengthen tax administration.
The proposed rule will apply from April 1, 2025.
Capital Gains Tax Framework
The Amendment Bill also proposes changes to capital gains tax on investment assets held by various investor categories, including Unit Trusts.
Paranavitane noted that quoted equities held by Unit Trusts are not expected to be affected. The existing exemption for listed equities remains unchanged.
The Association stated that capital gains tax treatment for other asset classes should also remain unchanged, provided Unit Trusts maintain their pass-through status. It added that it will engage stakeholders to seek clarity before implementation to avoid adverse effects on investors.
Market and Governance Impact
The Association said the proposed measures aim to improve transparency, strengthen tax compliance, and align with broader fiscal objectives.
Unit Trusts play a key role in expanding capital market participation and supporting long-term investment. The Association said it will continue working with regulators and policymakers to ensure smooth implementation and keep investors informed.
Last modified: March 3, 2026